


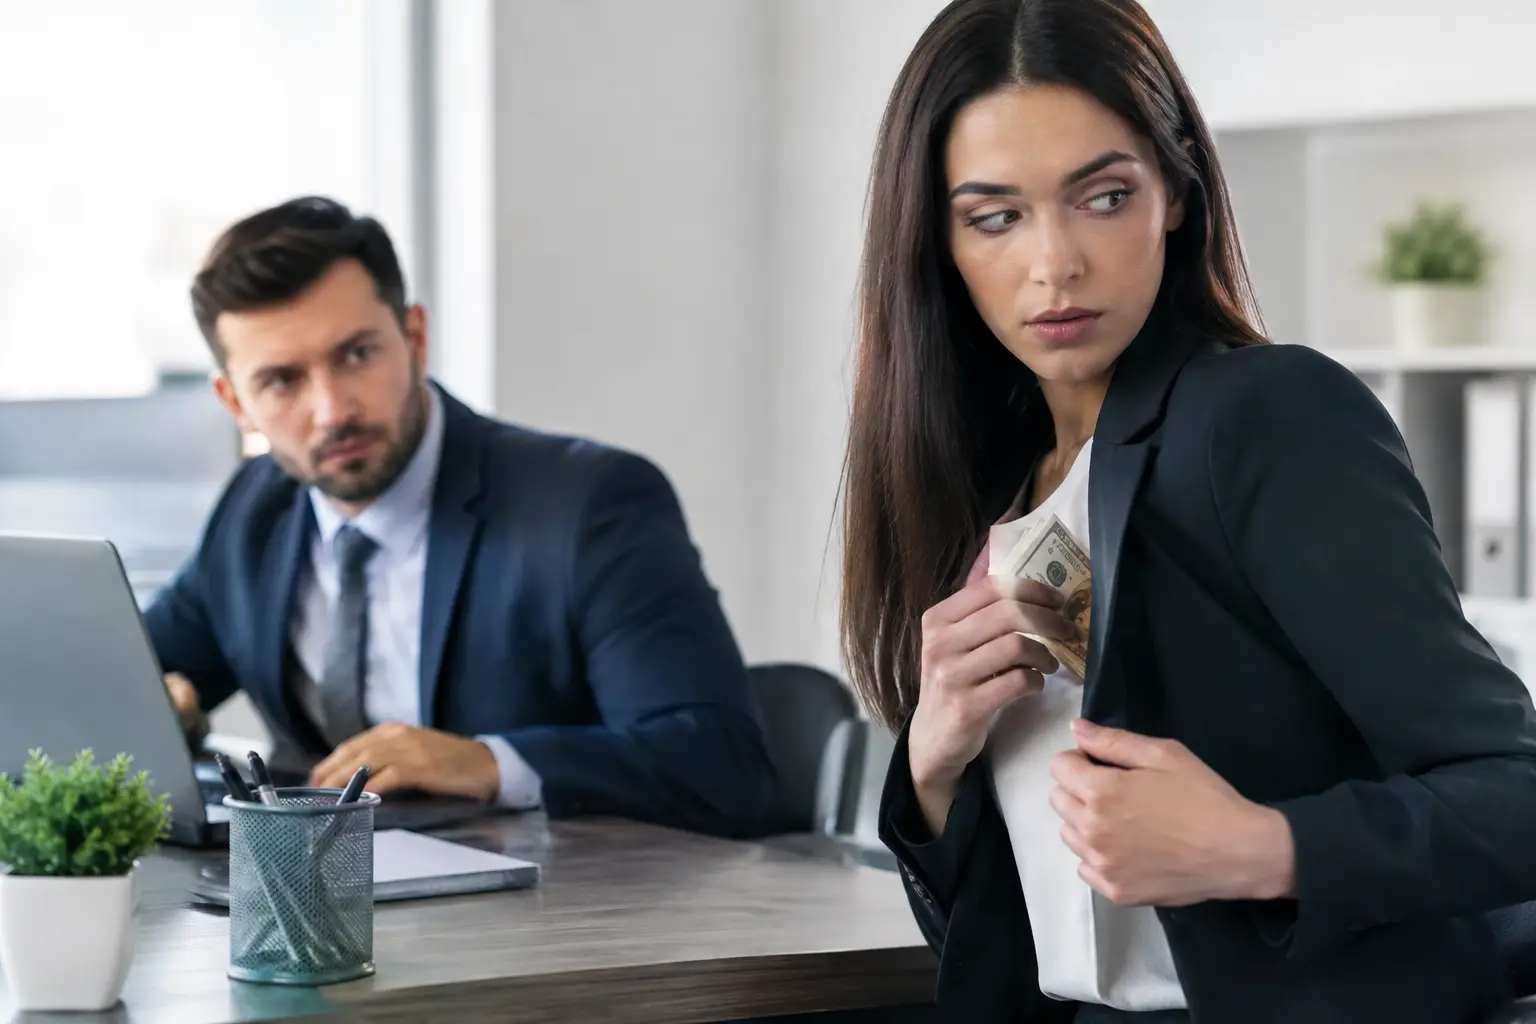
Identifying Employee Embezzlement at Work
A missing deposit rarely announces itself as theft. More often, it appears as a refund that cannot be explained, a vendor payment that keeps changing, a drawer that is always short, or financial records one employee refuses to let anyone review. Identifying employee embezzlement means recognizing these patterns early, without jumping to conclusions or putting the business at further risk.
For a business owner, executive, or fiduciary, the issue is not simply whether money is missing. It is whether the available facts can be verified, whether evidence will withstand scrutiny, and whether the response protects the company, its employees, and any future legal action. A rushed accusation can damage reputations and compromise an otherwise valid case. A careful investigation creates clarity.
What Employee Embezzlement Usually Looks Like
Employee embezzlement is the misuse or theft of assets entrusted to an employee. Those assets may be cash, inventory, customer payments, payroll funds, company credit cards, data, or equipment. It can occur at any level of an organization, although it is most often enabled by access, weak oversight, and too much control concentrated with one person.
The method depends on the business. In a retail setting, an employee may manipulate returns, void transactions, or remove cash before it reaches the register. In a professional office, the conduct may involve false invoices, altered expense reports, ghost employees, unauthorized transfers, or payments to a shell company. Construction, property management, medical practices, nonprofit organizations, and closely held businesses each have their own pressure points.
The key distinction is that an employee usually has legitimate access at the beginning. The wrongdoing is concealed within ordinary operations. That is why a single unusual transaction is not always meaningful. Repeated irregularities, unexplained exceptions, and records that do not reconcile are far more significant.
Warning Signs Worth Taking Seriously
No behavioral sign proves theft. An employee may be under personal financial strain, work long hours, or become defensive for reasons unrelated to misconduct. Still, changes in behavior can matter when they appear alongside accounting discrepancies or restricted access to records.
Common concerns include an employee who insists on handling a financial process alone, refuses vacations, works unusual hours without a clear business reason, or becomes upset when another person asks routine questions about accounts. A sudden lifestyle change may also deserve attention, particularly when it is inconsistent with known compensation. Expensive purchases alone are not evidence, but they may justify a closer review when paired with financial anomalies.
Operational signals are often stronger. Watch for recurring inventory shortages, deposits that arrive late, duplicate vendor payments, unexplained write-offs, voids or refunds that cluster around a particular employee, unusual customer account credits, and vendors with incomplete contact information. Bank reconciliations that are repeatedly delayed or adjusted without documentation should never be treated as a minor bookkeeping issue.
It also matters when one person controls several stages of a transaction. An employee who can create a vendor, approve an invoice, issue payment, and reconcile the bank account has an opportunity that should be addressed even if no fraud has been found. Internal controls are not a sign of distrust. They are a basic safeguard for honest employees and the organization alike.
Identifying Employee Embezzlement Without Making a Costly Mistake
When concerns arise, business leaders often want an immediate confrontation. That instinct is understandable, but it can create avoidable problems. A suspected employee may delete records, contact potential witnesses, alter files, or make allegations of retaliation or wrongful termination. The appropriate first step is usually to limit risk quietly while determining what the facts support.
Begin by preserving relevant records. Secure accounting files, email archives, bank statements, invoices, receipts, point-of-sale reports, payroll records, access logs, company devices, and surveillance footage under the company’s control. Document where the information came from, when it was collected, and who had access to it. This recordkeeping helps establish authenticity and protects the integrity of evidence.
At the same time, consider sensible interim controls. Reassign approval authority, require dual review of payments, change system permissions where appropriate, and conduct timely account reconciliations. These measures should be framed as normal business controls rather than punishment directed at one person. The goal is to prevent additional loss while avoiding an accusation before the evidence has been evaluated.
Avoid conducting a personal search of an employee’s belongings, accessing private accounts, or using monitoring methods that may violate company policy or state and federal law. California employers, in particular, should be careful about privacy expectations, workplace surveillance, wage issues, and electronic communications. Counsel can advise on employment-law obligations, while a qualified investigator can help determine what information may be obtained lawfully and how it should be documented.
Follow the Money and the Records
A credible embezzlement inquiry follows a defined process rather than a hunch. The investigation should identify the suspected loss, the relevant time period, the people with access, and the records capable of confirming or disproving the concern.
Financial analysis may compare sales to deposits, vendor payments to contracts and delivery records, payroll to actual staffing, or inventory purchases to inventory movement. Digital evidence can reveal when records were created or modified, whether files were deleted, and whether company systems were accessed outside normal business activity. In some cases, publicly available business records and discreet field investigation can help establish whether a vendor is legitimate or connected to an employee.
The scope should match the risk. A small cash shortage may call for a targeted audit and tighter controls. A pattern involving forged checks, fictitious vendors, diverted customer payments, or substantial asset loss may require a broader investigation coordinated with legal counsel, forensic accountants, and law enforcement when appropriate.
It is also essential to investigate objectively. The evidence may point to theft, but it may also reveal a training failure, bookkeeping error, vendor dispute, cyber compromise, or weak process. A professional investigation is valuable because it tests the allegation rather than trying to confirm it. That distinction protects everyone involved.
Why Discretion Protects the Business
Rumors can harm a workplace long before an investigation is complete. Limit knowledge of the inquiry to those with a genuine need to know, such as ownership, designated executives, counsel, and the professionals handling the matter. Do not discuss suspicions with coworkers, customers, vendors, or friends of the business.
Discretion is not about concealing misconduct. It is about preserving evidence, treating people fairly, and reducing the risk of defamation, retaliation claims, or unnecessary disruption. If an interview becomes necessary, it should be planned around the known facts, conducted professionally, and documented carefully. The order of interviews, the questions asked, and the timing of employment decisions can all affect the outcome.
For organizations facing a serious or sensitive concern, an independent investigator can provide a neutral fact-finding role. Kay & Associates Investigations approaches financial-fraud matters with the confidentiality, documentation, and investigative discipline required when business decisions may carry legal consequences.
Strengthening Controls After a Suspected Loss
Whether the investigation confirms embezzlement or exposes a control weakness, the business should treat the event as a reason to improve its systems. Separation of duties is one of the most effective safeguards. The person who authorizes a payment should not be the same person who enters it, releases it, and reconciles the account.
Regular bank reconciliations, independent review of expense reports, vendor verification, inventory counts, and clear approval limits can identify irregularities before losses grow. Mandatory vacations and cross-training also matter. Fraud is easier to hide when one employee is considered indispensable to a process no one else understands.
Technology can help, but software alone does not solve an oversight problem. Automated alerts are useful only when someone reviews them. The best controls are practical enough to be followed consistently and strong enough to make concealment difficult.
If you suspect financial misconduct, do not let uncertainty force an impulsive decision. Preserve what you can, restrict further exposure, and obtain qualified guidance before confronting the person involved. A measured, lawful response gives your business the best chance to protect its assets and move forward on verified facts.
Locating and Serving a Person Hard to Find for Legal Action says: